The family without borders: governance, succession and the Cayman Islands family office
An original version of this article was first published in IFC Review, October 2026.
For many international families, there is no longer an obvious answer to the question of where the family is permanently based. The business that created the family’s wealth may be headquartered in one country, while family members live, work and study in several others. Investments may be held through structures spanning multiple jurisdictions, alongside trusts, operating businesses, real estate, and philanthropic interests. The family’s professional advisers may be similarly dispersed.
Managing wealth and succession against that backdrop requires considerably more than loose plans and carefully synced diaries. Decisions must be made about who should participate in the management of family assets, how different interests and perspectives should be accommodated, when responsibility should pass between generations, and how younger family members should be prepared for the roles they may eventually assume. The task is a big one.
Getting structuring right for international families involves questions of governance and succession as much as wealth management. It necessitates a structure capable of bringing together the different people, assets, advisers and entities that comprise a modern international family’s affairs. For families with connections to multiple jurisdictions, the choice of where that family office sits – and how it interacts with the family’s wider structures – can be particularly important. The Cayman Islands is now a necessary part of that conversation.
A family without borders
The international spread of the modern family is not a new concept, but its practical consequences have become increasingly difficult to ignore. A family's geographical footprint can expand rapidly. Children educated overseas may remain there; marriages can introduce connections with additional jurisdictions; family businesses may expand internationally or be sold; and investment portfolios increasingly include assets located around the world.
The result can be a collection of companies, trusts, foundations, funds (among other vehicles), and relationships, established at different times, for different purposes and sometimes on advice from professionals in several jurisdictions. The challenge for a family office is to bring a degree of coordination to those arrangements without assuming that every family member, asset or structure can (or for that matter should) be treated in the same way. Doing so without causing unnecessary stress or disharmony within the family itself is a further challenge.
That task is particularly important where the family office sits alongside trusts and other fiduciary structures. The family office may have detailed knowledge of the family's objectives and investment strategy, but trustees and directors remain subject to their own legal and fiduciary duties. Similarly, a family council or investment committee may provide valuable input without necessarily having formal authority over the entities holding the family's wealth. Clear delineation of those roles, and clarity around boundaries, can become as important as the structures themselves.
Who makes the decisions?
Family governance can sound unnecessarily formal when the family is small and relationships are good. It tends to become more important when neither remains the case.
The transition from a wealth creator making decisions personally to a larger group of family members participating in those decisions can expose questions that previously did not need to be asked. Who determines investment strategy? Which decisions require consultation with the wider family? Should family members be entitled to work in the family business or family office? What happens when different branches have different financial needs or attitudes to risk?
In reality, it can be difficult to pinpoint a single governance model capable of answering those questions. Depending on the family, suitable arrangements may include a family council, investment or philanthropy committees, a family constitution or charter, independent advisers, and formal policies dealing with matters ranging from distributions to employment of family members. In all cases, the purpose should not be to create governance for its own sake, but to establish an understandable framework within which decisions can be made.
The legal structure must then work alongside that framework. Cayman trusts, including STAR trusts, private trust companies and foundation companies, provide considerable scope to allocate responsibility between family members, professional fiduciaries and independent participants. A foundation company, for example, can provide a familiar corporate framework while permitting governance arrangements to be designed around particular family or succession objectives. Its separate legal personality and flexible constitutional arrangements have contributed to its increasing use within family office and private trust company structures.
The important point is that informal family governance and formal legal governance should not be developed in isolation. A beautifully drafted family charter achieves little if it assumes powers which in fact belong to a trustee; equally, a technically sound trust structure may struggle if no thought has been given to how the family itself will participate in decisions.
The importance of succession planning
Succession planning is often discussed in terms of the transfer of wealth. For a family office, the transfer of responsibility can be just as significant, especially where a founder who has spent decades building a business or investment portfolio may personally hold an extraordinary amount of knowledge. Important contextual information, such as an understanding of individual investments and an analysis of the family's approach to risk, may never have been formally recorded. If the founder also makes most important decisions, a sophisticated legal succession plan may still leave a considerable practical gap.
The family office can play an important role in closing that gap. In terms of good governance, decision-making processes can be carefully documented and relationships with professional advisers formalised rather than left dependent on one individual. Ideally, the office becomes a first port of call for the family, giving them peace of mind that bespoke solutions will be tailored to fit their particular needs by experts who genuinely care for them. Where an operating business remains within the family, succession planning can address ownership separately from management, and consider whether the next generation will participate as executives, directors, shareholders, or simply beneficiaries of the wealth it generates.
Trust and estate planning remains an essential part of that exercise, particularly for families whose members are resident in different jurisdictions. However, a successful succession plan must also consider who will exercise influence, how decisions will be made, and whether those expected to assume responsibility have been prepared to do so (and are ready to lead when the time comes).
Choosing a successor
Deciding who is the next true leader in the family, and a responsible steward for the family office, can also be a difficult task. There can be a considerable distance between telling younger family members nothing about the family’s wealth and giving them unrestricted responsibility for it.
Ideally, next-generation planning should begin long before any formal transfer of wealth or control. Younger family members might attend family council meetings, participate in philanthropic initiatives, receive education about the family's businesses and investments, or sit as observers on investment committees. Responsibility can then increase over time according to aptitude and interest. Of course, not every member of the next generation will want the same involvement. One may be interested in the operating business, another in investment management and another in philanthropy; some may prefer no formal role at all. Effective planning does not necessarily require uniform participation, but it does benefit from clarity about the opportunities available and the responsibilities accompanying them.
Philanthropy can be particularly useful in this context. It gives younger family members an opportunity to make decisions collectively, evaluate competing priorities, and see the consequences of capital allocation without immediately transferring responsibility for the family's principal wealth. Cayman foundation companies and purpose trusts can provide useful vehicles where philanthropic or other family purposes form part of the wider structure. The overriding objective should not simply be to teach the next generation how to preserve an existing pool of assets. It is to equip them to understand the structures, responsibilities and values they may ultimately be asked to carry forward.
Building the right structure in the Cayman Islands
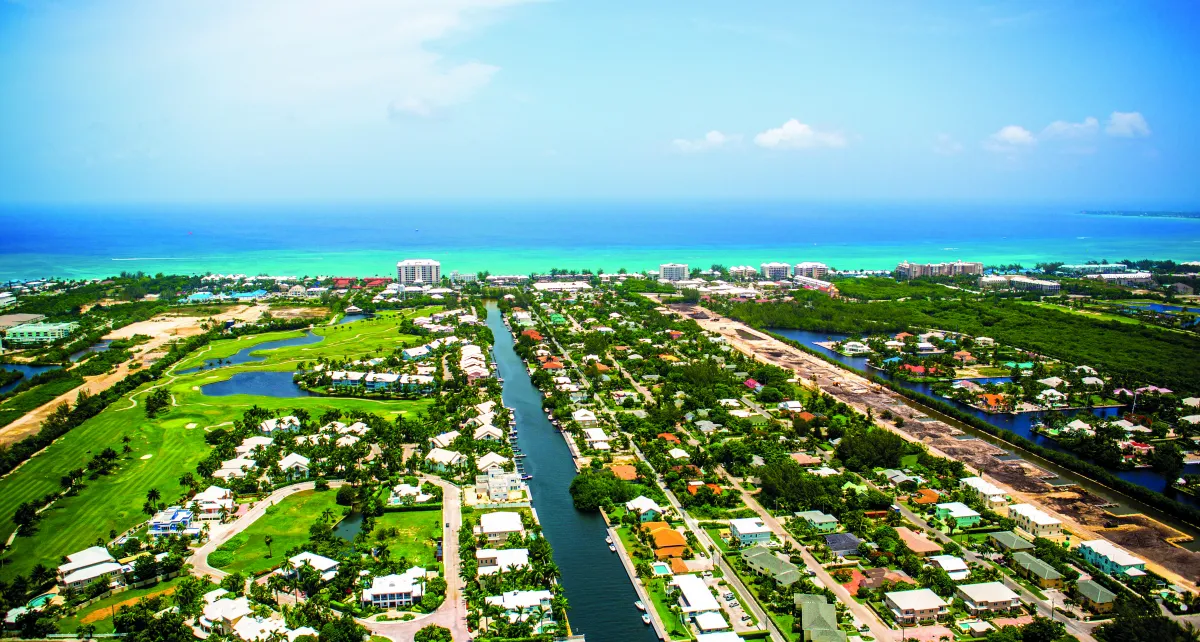
The Cayman Islands are recognised as one of the world's leading international financial centres, serving investment funds, private capital, multinational businesses, and increasingly, the needs of sophisticated international families. This positive reputation was earned through decades of strategic vision and adaptation to a changing global economy. Today, the jurisdiction combines political stability, a respected legal system grounded in English common law, world-class professional services, and a genuinely international population, to form a competitive service offering for family offices.
Central to succession arrangements in Cayman are trusts; STAR trusts, in particular, provide additional flexibility where structures combine beneficiaries with wider family, philanthropic or other purposes. Private trust companies can permit greater family involvement in trusteeship and governance. Foundation companies offer a separate legal personality and a flexible framework, which can be particularly attractive to families familiar with corporate or civil-law structures. Those wealth-holding arrangements sit alongside Cayman's well-established investment funds sector, which is an increasingly significant connection as family offices adopt more institutional approaches to investment. Private equity, private credit, venture capital, real estate, infrastructure, co-investments and other alternative strategies can require structures and service providers more traditionally associated with institutional investors.
Cayman's existing professional infrastructure therefore allows a family office to draw upon local investment, fiduciary, legal, accounting and administration expertise to ensure good governance, while continuing to work with advisers wherever individual family members and assets are located. Regulation also plays a key role: the family office's ownership and activities must be considered in determining whether particular licensing or registration requirements apply and are subject to ongoing monitoring.
A Cayman base for an international family
Recent Cayman experience points towards family offices becoming an increasingly visible part of the jurisdiction's private wealth landscape. This includes greater use of Cayman structures by family offices investing in private markets, increasing interest in foundation companies and private trust company arrangements, and a broader focus on family governance and succession alongside conventional wealth preservation.
The value of the family office to an international family is not that it removes cross-border complexity. Properly structured, it provides a means of managing it. Governance, succession and next-generation planning are ultimately different aspects of that same question. For Cayman, that presents an opportunity extending beyond the establishment of individual trusts, companies or investment vehicles. The modern family office can provide the connective tissue between those structures and the family they are intended to serve. And, for the family without borders, having a clearly defined centre may matter more than ever.